

Latin America’s steel industry warned that it is facing one of the most complex periods in recent years due to the growth of steel imports from China, a phenomenon that has increased competition in regional markets and put pressure on the profitability of local producers.
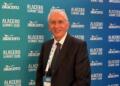
“The latest report published by Alacero through Margaret Myers indicates that 5% of China’s GDP is allocated to industrial subsidies. That’s more than $900 billion per year, which, to put it in perspective, is roughly equivalent to 50% of Mexico’s Gross Domestic Product,” said Ezequiel Tarvernelli, director of the Latin American Steel Association (Alacero).
In a meeting with the media on the first day of the Alacero Summit 2026 , he mentioned that currently four out of every 10 tons of steel consumed in the region come from imports, mainly from China or re-exported through third countries.
This situation, he said, creates market distortions that affect investment, employment, and the development of high value-added industrial chains.
He mentioned that Latin America has relevant competitive advantages, including availability of raw materials, access to energy, installed technological capacity and specialized personnel; however, he considered it essential that governments promote policies that guarantee equitable competitive conditions against economies that maintain large-scale industrial support programs.
He explained that steel is a strategic input for activities such as construction, vehicle manufacturing, energy infrastructure and industrial projects, so preserving a solid productive base is key to the region’s economic growth.
He simply mentioned that in recent years the Latin American steel industry has maintained important investment programs to modernize plants, increase operational efficiency and advance in decarbonization processes.
Given this scenario, Ezequiel Tarvernelli said that among the measures proposed by the sector are trade defense mechanisms , greater monitoring of imports, as well as industrial policies aimed at strengthening regional supply chains.
They also called for deeper productive integration with North America, given the opportunities arising from nearshoring and the growing demand for manufactured goods in the United States.
Similarly, he pointed out that the challenge is not limited to steel, but involves the competitiveness of sectors ranging from auto parts and machinery to construction and infrastructure.
Comment and follow us on LinkedIn: @Evangelina del Toro / @GrupoT21